Nobody can tell you from the outside whether your policy will pay. Only your policy wording and your insurer can do that. What a restoration crew can do is help you collect the kind of records that make the conversation with your insurer clearer, and that starts while the water is still wet.
This page is general guidance, not legal or coverage advice. Policies and endorsements differ, and a claim decision belongs to the insurer.
Sudden and accidental versus slow and ignored
Most homeowners policies are written around a simple split. Water damage that arrives suddenly and by accident, such as a supply line that bursts or a water heater that fails overnight, is often treated as a covered event. Damage that builds slowly over weeks or months, such as a drip under a sink nobody fixed, is often treated as maintenance and is frequently excluded.
The word often matters in both directions. Some policies cover the resulting damage but not the repair of the failed part itself. Others limit mold or water backup unless you bought an add-on. Your policy language decides, so ask your insurer which category your loss most resembles.
Quick reference by type of water event
| Type of water event | Often covered or often excluded | What to do first |
|---|---|---|
| Burst supply line or pipe | Often covered when sudden | Shut the valve, photograph, start drying |
| Water heater failure | Often covered when sudden | Turn off the supply, document the tank and floor |
| Slow drip under a sink or behind a wall | Often excluded as gradual | Fix the leak, keep dated photos and the repair receipt |
| Roof leak during a storm | Depends on roof condition and policy | Tarp if safe, photograph the ceiling and the roof |
| Sewer or drain backup | Often needs a backup endorsement | Stay out, call the sewer utility or plumber, then document |
| Flood or rising surface water | Excluded from standard homeowners policies | Check for a separate flood policy before anything else |
Treat the middle column as a starting point for questions, not an answer.
Flood is a different animal from a pipe failure
The California Department of Insurance states that standard homeowners insurance does not cover flood damage. Policies typically exclude flood, mudslide and debris-flow losses. If water comes in from outside, from a creek, a drainage channel or a hillside, it is usually a flood question and not a pipe question.
Flood coverage comes from the National Flood Insurance Program or a private flood policy. NFIP policies generally take effect 30 days after purchase, so buying one when the storm is already in the forecast does not help that storm. If a loss involves rising water, a crew trained for flood damage restoration can document the extent while you contact the right insurer.
Water in the house right now?
Call (805) 291-8940 for same-day response when available. Scope and price are explained before work starts.
What to photograph and what to keep
Start with wide shots of each affected room, then close-ups of the source and of every damaged surface. Add a short video walking through the space with the water visible.
- The failed pipe, fitting, appliance or roof area, before anyone removes it
- Wet flooring, baseboards, cabinet bases and the lower foot of the walls
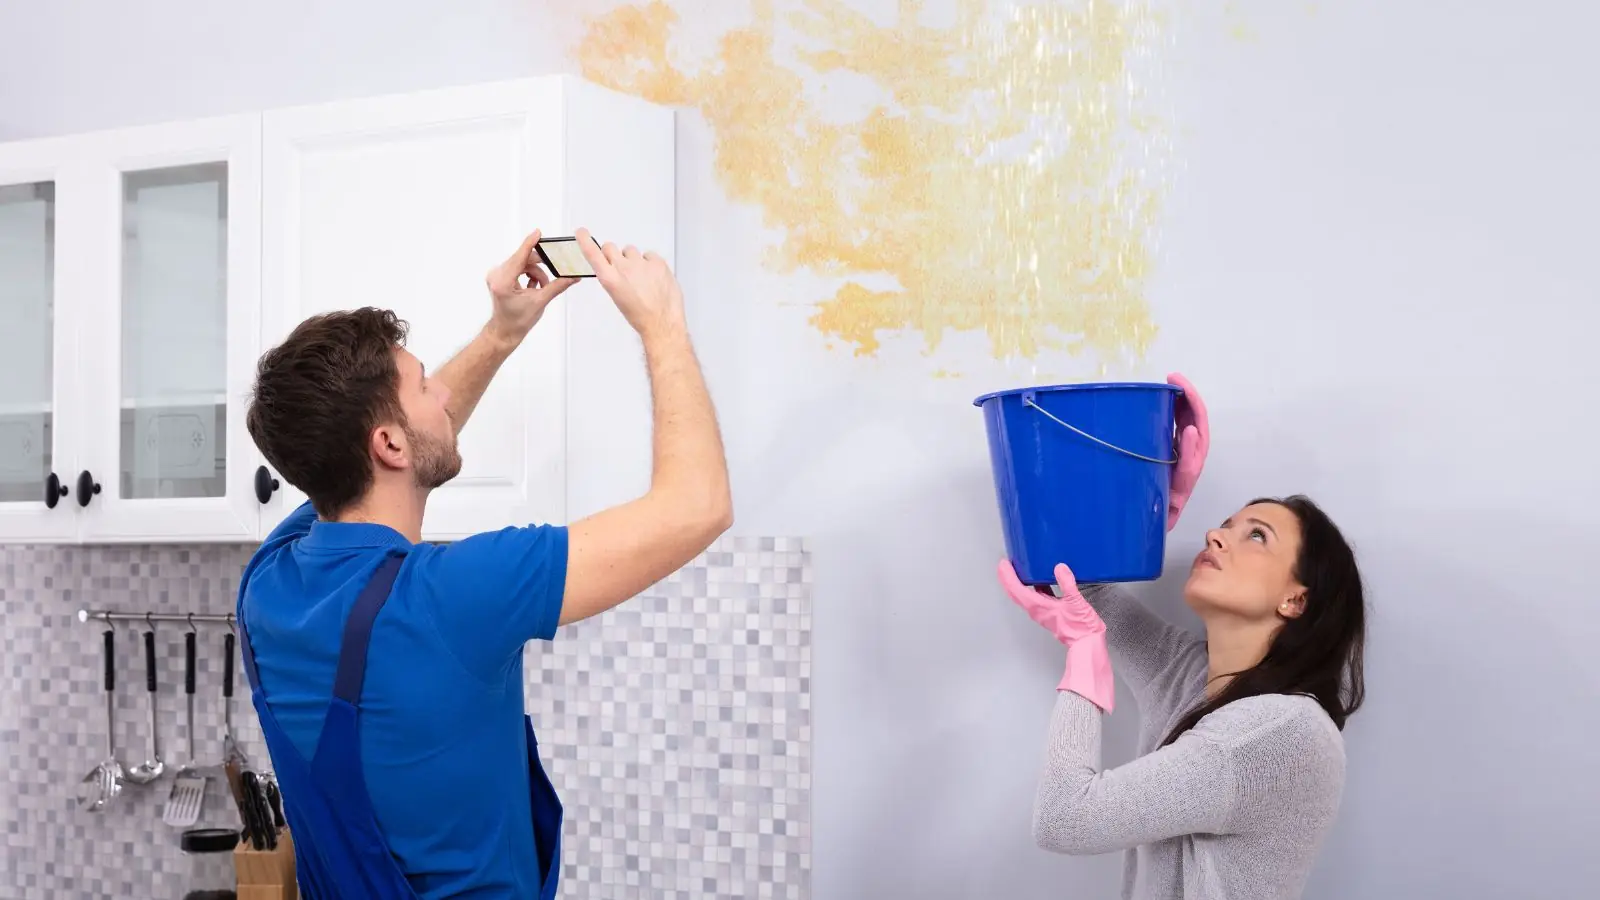
- Ceiling stains with a tape measure or a coin for scale
- Damaged belongings, with brand labels and model numbers visible
- Plumber, roofer or appliance repair invoices and any parts you keep
- Every receipt for emergency purchases such as fans, tarps or hotel nights
Keep damaged items until your insurer says you may discard them, unless they are a sanitation problem.
Why a written scope and a moisture log help
A claim conversation goes better with numbers than with adjectives. A written scope lists the rooms, the materials involved and the work planned. A moisture log records readings from moisture meters and a thermal imaging camera at the start and on each return visit, so the drying progress is visible on paper.
Documentation like this does not decide coverage. It shows what was wet, what was done and when the structure reached dry standards. Crews that follow ANSI/IICRC S500 practice build this record as a normal part of water damage cleanup, and you can ask any company whether theirs does.
File promptly and mitigate right away
Most policies expect you to report a loss soon after it happens and to take reasonable steps to stop further damage. That second duty is why drying should not wait for a final answer. Wet drywall and carpet pad can develop mold growth in the days that follow, and a larger loss is harder to explain than a contained one.
Call your insurer, give the facts plainly, and ask what they need from you. Write down the date, the name of the person you spoke with and any claim reference. If you are unsure whether to proceed with emergency water removal before an adjuster visits, ask that exact question on the call.
Electrical and sewage warning
If water has reached outlets, the panel or appliances, stay out of the room. Cut power only if the breaker panel can be reached on dry floor. Call the utility or 911 for any electrical or gas risk before calling the restoration line. Sewage backup is a separate hazard, so keep people and pets away.
Questions worth asking your insurer
- Is my loss treated as sudden and accidental, or as gradual?
- What is my deductible for water damage specifically?
- Do I have water backup or flood coverage, and what are the limits?
- Does coverage include tear-out of walls and flooring to reach the leak?
- What documentation do you want from the mitigation company?
Ask for the answers in writing when you can. If the loss reaches into several areas of the house, restoration crews in nearby communities such as Thousand Oaks and Oak Park work from the same documentation habits, so the paperwork you build is not tied to one street.
Newbury Park water and weather notes
A flood-control channel runs along the US 101 corridor, and Arroyo Conejo is the main waterway through Newbury Park. That does not tell you whether your own address is exposed. Look up your address on FEMA's Flood Map Service Center before you decide whether a separate flood policy is worth pricing.
The California Department of Insurance notes that NFIP flood means a general and temporary condition of partial or complete inundation of at least two acres of normally dry land or two or more properties. Earth movement is generally excluded. If a slope or hillside gave way, ask your insurer which part of the loss falls under which policy.
The Department also says the California FAIR Plan does not cover storm-related damage unless the owner holds a difference-in-conditions policy from another insurer. If your coverage comes through the FAIR Plan, read your own wording before winter rain arrives and ask what else you would need.
Sources: California Department of Insurance, FEMA Flood Map Service Center
Frequently asked questions
Does homeowners insurance cover a burst pipe?
Often yes when the break was sudden and accidental, but your policy wording and deductible decide. Some policies cover the water damage but not the cost of fixing the pipe itself.
Report it promptly, document everything, and start drying so the loss does not grow.
Will insurance cover slow leaks?
Gradual leaks and long-term seepage are often excluded as maintenance issues. Some policies allow limited coverage if the leak was hidden and could not reasonably have been found.
Ask your insurer directly, and keep repair records showing when you found and fixed the leak.
Does a standard policy cover flood?
No. The California Department of Insurance says standard homeowners insurance does not cover flood damage. Flood coverage is bought separately through the NFIP or a private insurer.
Can the restoration company tell me if I am covered?
No. Only your insurer decides coverage. A restoration company can provide a written scope, photos, moisture readings and invoices that support your claim conversation.
I just bought a flood policy. Am I covered for the storm this week?
Probably not yet. NFIP policies generally take effect 30 days after purchase, with an exception when a federally regulated lender requires coverage on a mortgage in a designated high-risk area.
Ask your agent for the exact effective date in writing, and look up your address on FEMA's Flood Map Service Center to see how your property is mapped.